Quick Summary / Key Takeaways
- Business and personal finances are connected, but they should be planned with clear boundaries.
- Retirement planning, tax planning, insurance, and investment decisions should work together rather than in isolation.
- Succession planning prepares for a transfer of ownership, while exit planning focuses on the broader process of leaving the business.
- Starting these conversations early can give you more time to evaluate your options and make informed decisions.
Introduction
Owning a business gives you control over many financial decisions, but it can also make your financial life more interconnected. Your income, investments, retirement plans, insurance needs, and long-term goals may all be influenced by the business you operate.
That is why financial planning for business owners needs to look beyond the business itself. A thoughtful plan considers how business decisions affect your personal finances, and how your personal goals may influence decisions about the business.
For an operating business owner, the planning process often develops in stages. It starts with creating a clear separation between business and personal finances, then moves into retirement planning, tax considerations, risk management, and eventually succession planning or exit planning.
Separating Business and Personal Finances
One of the foundations of financial planning for small business owners is understanding where business finances end and personal finances begin.
Your business may be a major source of household income and wealth, but that does not mean every financial decision should be treated as a business decision. Keeping the two areas organized can make it easier to understand your financial position and make decisions with greater clarity. Your business structure, compensation approach, cash flow, and ownership interests can all create points where business and personal planning overlap.
Understand the role of your business in your financial plan
Start by considering how much of your overall financial picture depends on the business.
For many owners, the business represents more than an income source. It may also represent a significant portion of their long-term wealth. That concentration can make it important to consider the business alongside personal investments, retirement assets, insurance, and other financial resources.
Your financial plan should account for how these pieces fit together while you maintain clear records and boundaries between business and personal finances.
Consider owner compensation
Owner compensation is another area where business and personal planning intersect.
The way you receive income from the business can affect your household cash flow and the resources available for saving and investing. Rather than looking at compensation only as a business expense, consider how it fits into your broader financial goals. Compensation decisions can also depend on the business’s entity structure and tax circumstances, so coordination with your tax professional may be appropriate.
This is one reason business owner financial planning should address the business and household together while still keeping their finances clearly organized.
Keep personal goals visible
Business owners can spend years reinvesting in their companies. That may support the business, but it can also make it easy to postpone personal financial goals.
A comprehensive plan can help you consider questions such as:
- How much wealth is outside the business?
- What role should the business play in your long-term financial security?
- Are personal savings and investments keeping pace with your goals?
- What would your finances look like if your role in the business changed?
These questions become especially important as you begin thinking about retirement or a future transition.
For a broader look at how business ownership can shape personal wealth decisions, see our wealth management for entrepreneurs guide.
Choosing a Retirement Plan
Retirement planning can be particularly important for a business owner because the business itself may already represent a substantial long-term asset.
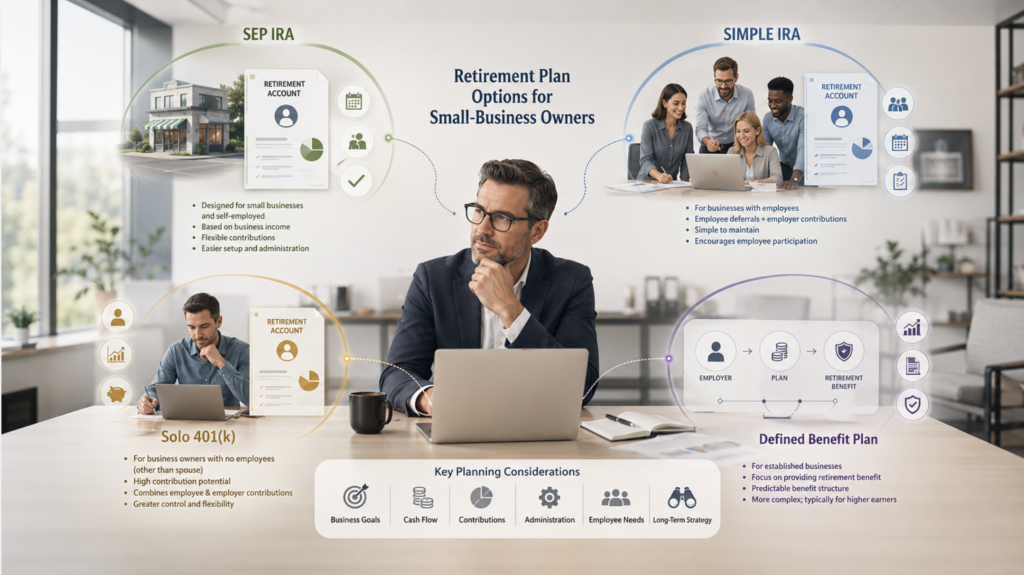
The retirement plan that fits a business depends on factors such as the structure of the business, employees, cash flow, and the owner’s broader financial objectives. Several types of plans may be relevant to small business owners, including SEP plans, SIMPLE IRA plans, one-participant 401(k) plans, often called solo 401(k)s, and defined benefit plans.
Each structure has different characteristics, requirements, and planning considerations.
SEP plans
A SEP is an employer-funded retirement arrangement in which the employer contributes to SEP-IRAs for eligible employees. A business of any size, including a self-employed individual, may establish one.
The details of how contributions work and who is covered depend on the plan and applicable rules.
SIMPLE IRA plans
A SIMPLE IRA plan is another option designed for certain small businesses. It can provide a way for employees and business owners to participate in retirement savings through the business. Employees may make salary-reduction contributions, while the employer is generally required to make contributions under the plan’s rules.
Its structure differs from other retirement plan types, so the business owner’s circumstances matter when evaluating whether it fits.
Solo 401(k) plans
A solo 401(k) may be available to a business owner with no employees other than a spouse, subject to applicable eligibility requirements.
Its design can differ from other retirement arrangements, making it another structure worth understanding as part of the planning process.
Defined benefit plans
Defined benefit plans are structured differently from defined contribution arrangements. They are designed around a specified retirement benefit and can involve more complex planning and administration.
For a business owner, comparing these options is not simply about choosing the plan with the most attractive feature. The decision should be considered in the context of the business, employees, cash flow, retirement objectives, and overall financial plan.
Because retirement plan rules can change, specific contribution limits and other thresholds should be evaluated using current, applicable guidance.
Tax Planning Across the Business and the Household
Business and personal taxes can be closely connected for an owner. A decision made within the business can affect the household’s financial picture, which is why tax considerations belong in the broader planning conversation.
Financial planning for business owners should consider how business income, owner compensation, investments, retirement savings, and other financial decisions interact.
Look at decisions across both sides
A business decision may make sense when viewed only through the company’s finances but have a different effect when considered alongside the owner’s personal goals.
For example, decisions about compensation, retirement plan structure, investments, or the timing of a business transition can have implications beyond the business itself.
The goal is not to predict future tax rules or make decisions based on a single tax year. Instead, it is to understand how different financial decisions fit together and coordinate with appropriate tax professionals when specific tax advice is needed.
Coordinate financial and tax planning
Financial planning does not replace tax advice. Instead, the two can work together.
A financial plan can identify decisions that deserve attention and help organize the broader picture. Your tax professional can then provide advice based on your specific circumstances and current tax rules.
This coordinated approach can help you evaluate decisions with a clearer view of both business and household considerations.
Risk, Insurance, and Key Person Exposure
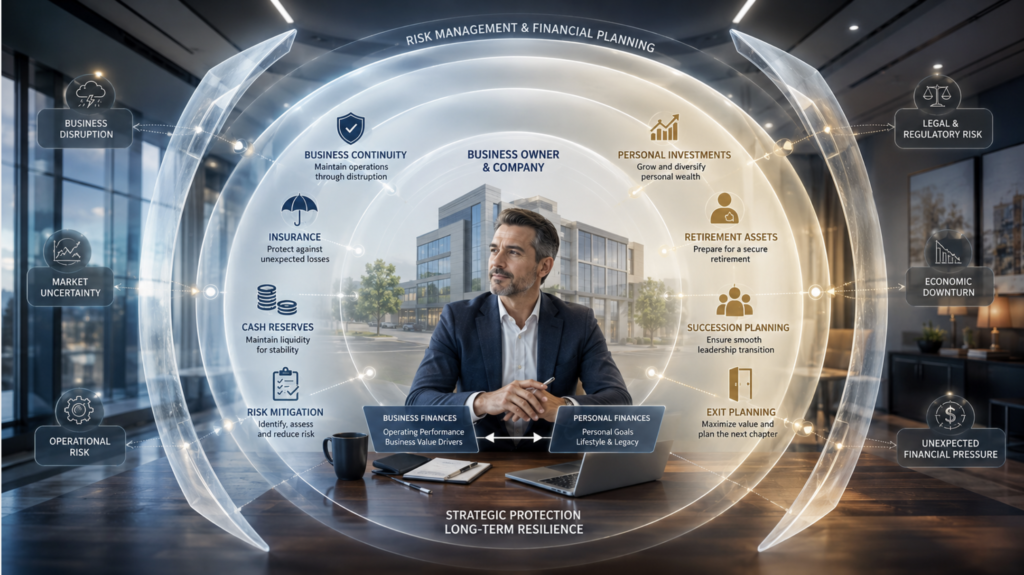
Business owners often have a significant amount of financial exposure tied to the continued operation of the company.
That exposure makes risk management an important part of financial planning for business owners. For an operating business, that can include evaluating the owner’s income risk, dependence on key people, and how an ownership transition would be funded.
Consider your personal income risk
If your household depends heavily on business income, an unexpected change in your ability to work can affect more than the company.
Disability insurance may be one consideration when evaluating how your personal income and financial goals could be affected by an extended inability to work. Depending on the policy, disability insurance may provide income when an insured person is unable to work because of a qualifying disability.
The appropriate coverage depends on the individual’s circumstances and should be evaluated as part of the broader financial plan.
Consider key person risk
A business may also depend heavily on one or more individuals whose knowledge, relationships, leadership, or skills are difficult to replace.
This is commonly referred to as key person risk. Key person life insurance may be purchased by a business on the life of an individual considered important to its operations, with the business generally serving as the policy owner and beneficiary.
Understanding that exposure can help an owner identify potential vulnerabilities and consider whether insurance or other planning strategies have a role in addressing them.
Review buy-sell funding
If a business has multiple owners, a buy-sell arrangement can establish a framework for what happens when an owner leaves under certain circumstances.
Funding can be an important part of that arrangement. Life insurance may be one funding option, depending on the terms of the agreement, the circumstances of the owners, and the structure involved. The funding approach should be evaluated alongside the terms of the agreement, the owners’ needs, and relevant tax and legal considerations.
These decisions should be coordinated with appropriate legal, tax, and insurance professionals.
Succession Planning for Business Owners
Succession planning for business owners focuses on how ownership and leadership may transfer from one person or group to another.
The transfer could involve family members, business partners, or employees. The important point is that succession is about more than identifying who takes over.
It can also involve preparing the business, the people involved, and the owner’s personal financial plan for the transition.
Transferring the business to family
Some owners want the business to remain within the family. That can create financial, operational, and personal considerations that deserve careful attention.
Questions may include who will take ownership, who will manage the business, and how the owner’s financial needs will be addressed after the transition.
Transferring ownership to partners
A partner-to-partner transition can involve its own planning considerations, particularly when the business has multiple owners.
The financial arrangement, funding, timing, and responsibilities associated with the transfer should be considered well before the transition occurs.
Transferring ownership to employees
Employee ownership can provide another possible succession path for some businesses.
As with other transitions, the process involves more than identifying a future owner. The financial and operational implications should be considered alongside the owner’s personal goals.
Succession planning can take time, so considering these questions well before an anticipated transition can provide more time to evaluate the available options. Depending on the structure of the transfer, coordination with legal, tax, valuation, and financial professionals may also be appropriate.
Exit Planning and Sale Readiness
Exit planning for business owners addresses the broader process of preparing to leave the business.
An exit may involve a sale, transfer, or another change in ownership. Regardless of the path, planning ahead can provide more time to understand the financial implications.
Understand what can affect business value
Business value can be influenced by factors such as financial performance, operations, customer relationships, management structure, and the business’s ability to operate beyond the current owner.
The specific valuation process depends on the business and the circumstances involved.
For an owner considering an eventual sale, understanding the factors that may influence value can help identify areas that deserve attention before a transaction is pursued.
Consider timing
The timing of an exit can affect both the business and the owner’s personal financial plan.
A business owner may need to consider whether the business is prepared for a transition, whether personal finances can support the next stage, and what other financial decisions may need to happen around the same time.
An exit can therefore be viewed as a financial planning event, not simply a business transaction.
Plan for the proceeds
Selling a business can change the owner’s financial picture substantially.
Before an exit, it can be useful to consider what the proceeds may mean for personal investments, retirement income, risk management, and long-term goals.
The proceeds may become a significant part of the owner’s personal wealth, so decisions about how those assets fit into the overall financial plan deserve careful consideration.
When to Bring in a Financial Advisor
A financial advisor for business owners can help connect decisions that might otherwise be handled separately.
You do not necessarily need to wait until you are ready to sell the business to begin a planning conversation. Planning can be relevant much earlier, while there is still time to evaluate different paths.
You may want to consider working with an advisor when:
- Your business has become a major part of your overall wealth.
- You are trying to coordinate business and personal financial goals.
- You are evaluating retirement plan options.
- You want to review insurance and financial risks.
- You are beginning to think about succession.
- You are considering a future sale or other exit.
- You want a more integrated view of your financial decisions.
At Liberty One Wealth Advisors, we believe financial planning should help you understand your choices and evaluate the tradeoffs involved. Our approach considers your broader financial picture so that business decisions and personal goals can be evaluated together.
Frequently Asked Questions
What is different about financial planning for a business owner?
Financial planning for a business owner differs because business and personal finances are often closely connected. The business may provide income, represent a significant portion of their wealth, and influence retirement and long-term financial goals.
Financial planning for business owners considers these connections while keeping business and personal finances clearly organized. It can include retirement planning, tax considerations, insurance, investment management, and eventual succession or exit planning.
Which retirement plan is right for a small business owner?
There is no single retirement plan that is appropriate for every business owner. SEP plans, SIMPLE IRA plans, one-participant 401(k) plans, often called solo 401(k)s, and defined benefit plans each have different structures and considerations.
The appropriate option depends on factors such as the business structure, whether the business has employees, cash flow, and retirement objectives. A comparison should remain focused on the characteristics of each plan and how they relate to the owner’s circumstances rather than assuming one structure is universally better.
How should I separate business and personal finances?
Start by keeping business and personal accounts, expenses, and records clearly separated. Business accounts, expenses, and records should be distinguished from personal finances, while the overall plan recognizes how the two areas affect each other.
It is also important to understand how owner compensation, business value, personal investments, retirement savings, and household goals fit together.
What is exit planning and when should it start?
Exit planning for business owners is the process of preparing for a future transition away from business ownership. It can involve understanding business value, considering potential buyers or successors, evaluating timing, and planning for the financial impact of the transition.
There is no universal starting point for every owner. Beginning the conversation before an exit is imminent can provide more time to evaluate options and prepare both the business and personal financial plan.
What is the difference between succession planning and exit planning?
Succession planning generally focuses on who will take over ownership or leadership of the business. The successor could be a family member, partner, or employee.
Exit planning is broader. It focuses on the owner’s overall transition away from the business and can include preparation for a sale, transfer, valuation considerations, timing, and the financial plan for the proceeds.
The two can overlap, but they address different parts of the transition process.
When should a business owner work with a financial advisor?
A business owner can benefit from financial planning well before retirement or a business sale becomes imminent.
An advisor may be particularly helpful when business wealth becomes a significant part of the owner’s financial picture, when retirement planning becomes a priority, or when the owner begins considering succession or an eventual exit.
The earlier these decisions are considered, the more opportunity there may be to evaluate different options as part of a coordinated financial plan.
A More Connected Approach to Business Owner Financial Planning
Your business may be one of the most important financial assets you have, but it is only one part of your financial life.
Effective business owner financial planning brings the business and household into the same conversation without treating them as the same thing. It considers where you are today, what you want your financial life to look like in the future, and what decisions may help connect the two.
From retirement planning and risk management to succession and exit planning, the goal is greater clarity around the choices ahead.
If you are looking for a financial advisor for business owners, Liberty One Wealth Advisors can help you evaluate your financial picture through an objective, holistic planning approach.
Disclosure
This article is provided for general educational and informational purposes only and should not be considered individualized investment, tax, legal, or financial advice. Financial planning and investment decisions depend on each individual’s circumstances, goals, and needs. Tax laws, retirement plan rules, and other regulations may change over time. Consult with qualified financial, tax, and legal professionals regarding your specific situation.